MONITOR
See whether change is taking hold
Check early premium and volume signals after underwriting changes, before claims experience develops.
The measures, explained
- CCR
- Claims and Commission Ratio: claims and commission as a percentage of earned premium, excluding overhead expenses.
- IBNR
- Incurred But Not Reported: reserves for claims costs yet to emerge in full.
- Attritional claims
- More frequent, lower-value claims, distinct from separately classified large and weather losses.
Review the months since implementation
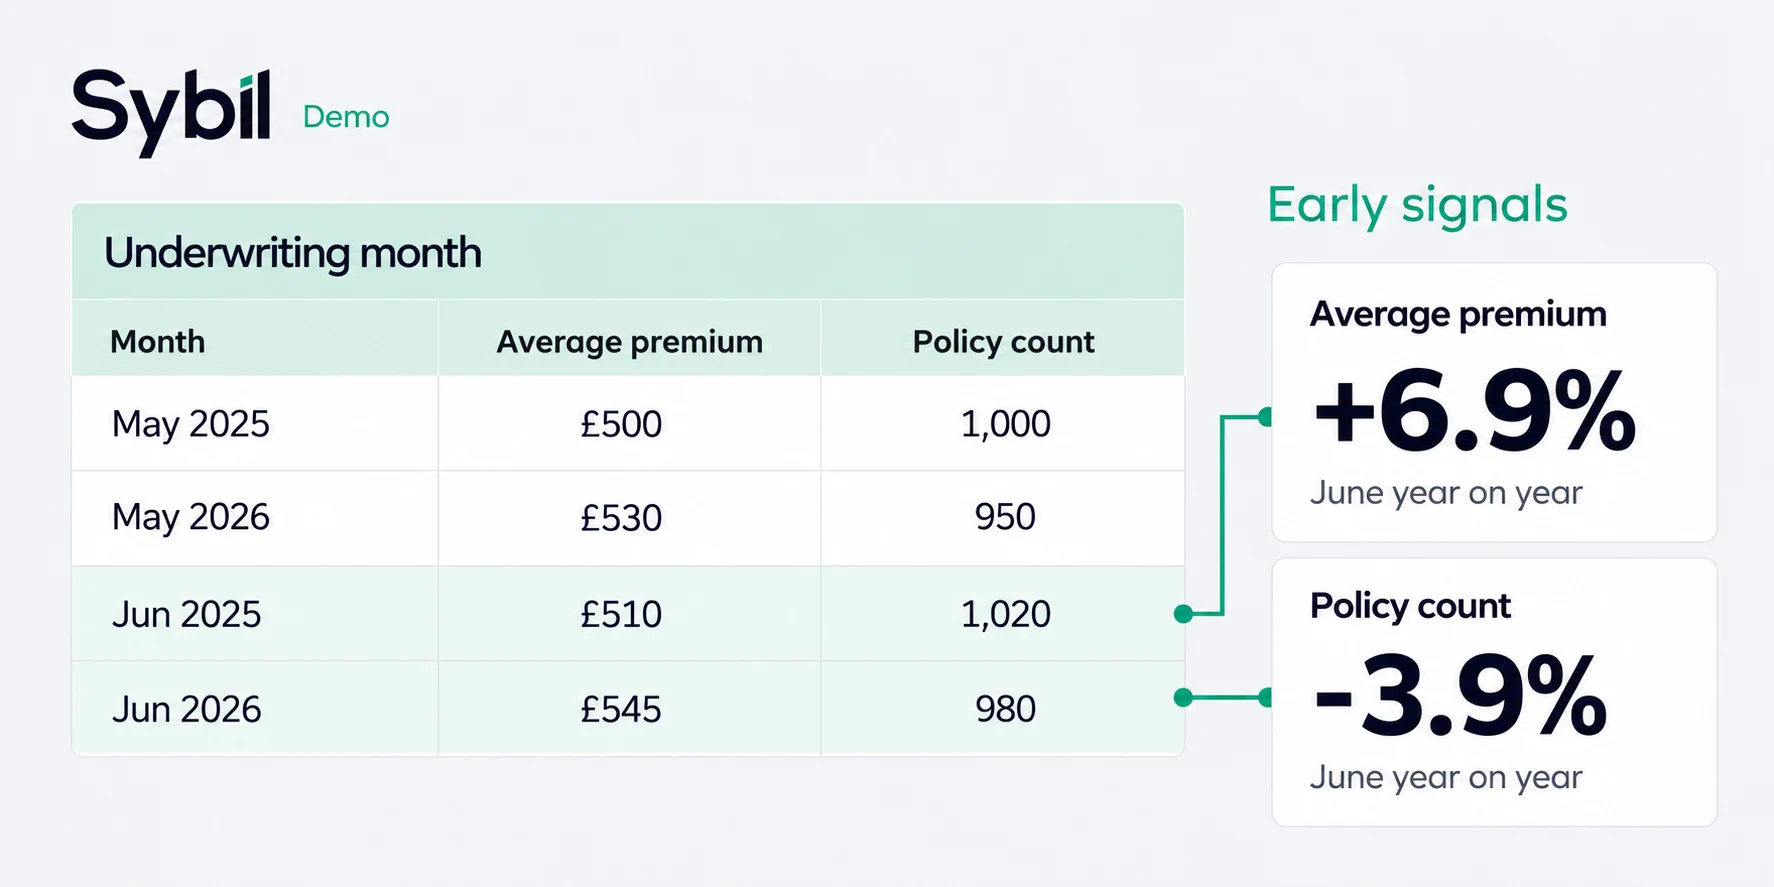
Use the exposure columns in an underwriting-month view to examine average premium and policy count after your underwriting changes went live.
Compare like months
Compare each month with the same month last year. Has average premium moved in the expected direction? How has policy count changed, and what does that suggest about volume?
Use the signal to guide follow-up
Treat the result as an early sense check. Investigate unexpected movements and follow up as claims emerge to assess whether performance is developing as intended.
An early checkpoint for action, before the claims picture matures
Average premium also reflects changes in business mix, exposure and cover; it is not a pure measure of rate change.
Let’s put it into practice
See how this could work for your portfolio
A portfolio challenge, an upcoming review or a different way of working. Let’s explore it together.
Book a demo