MODEL
Build triangles around the question
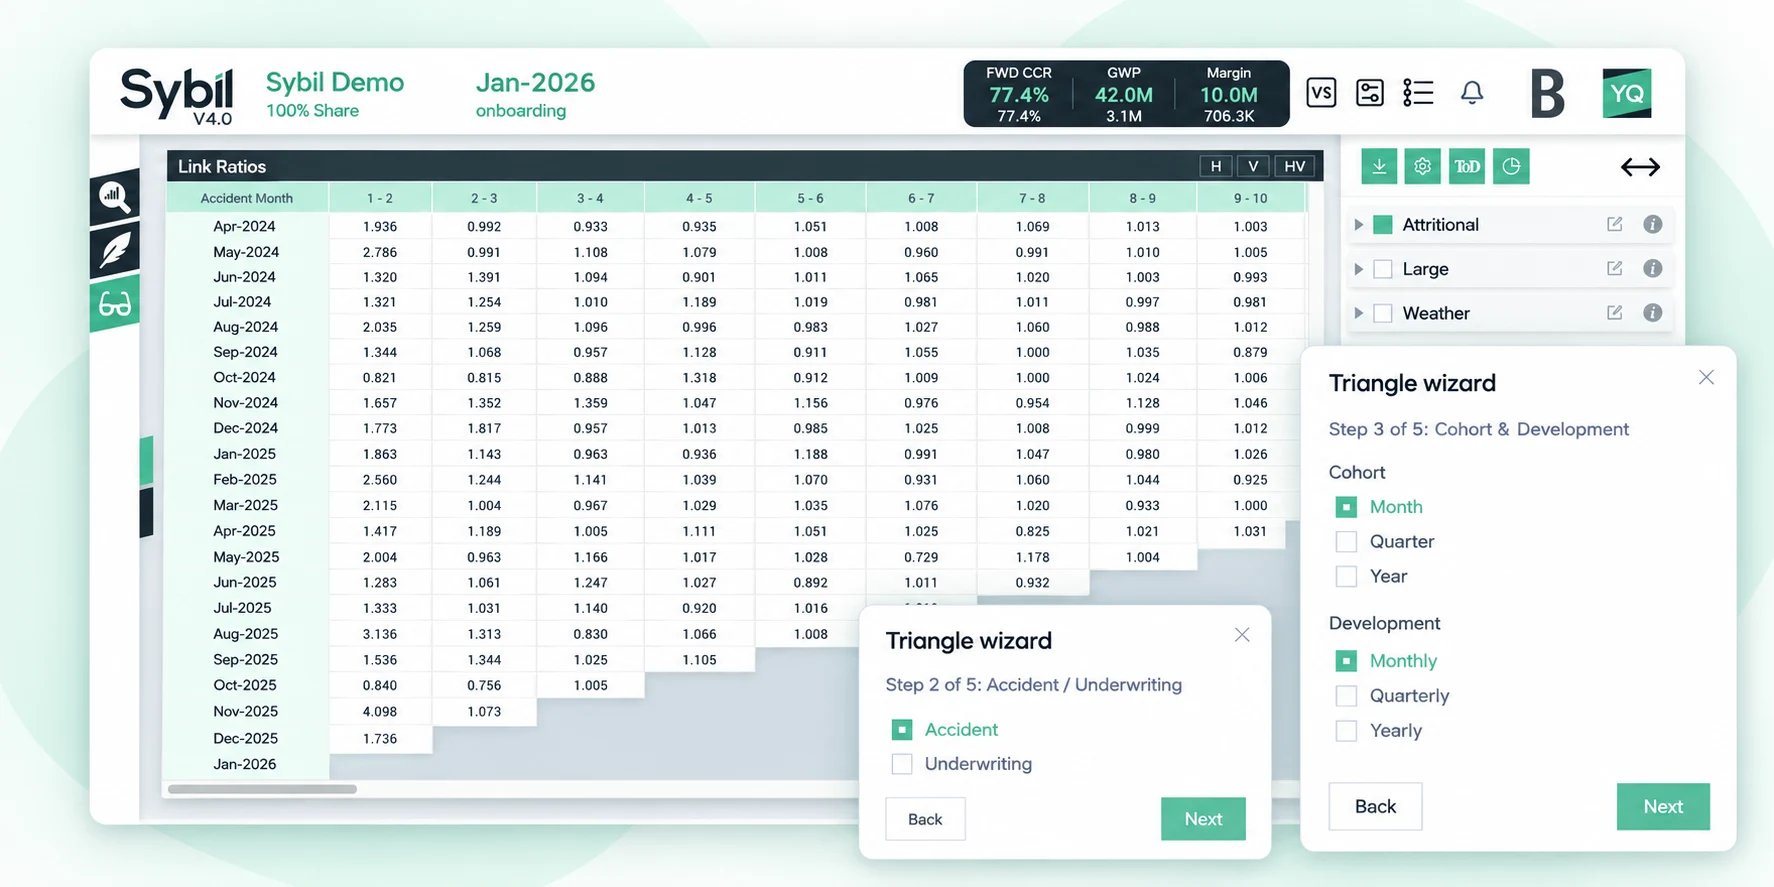
Shape the claims development view to fit the portfolio and the decision you need to support.
The measures, explained
- CCR
- Claims and Commission Ratio: claims and commission as a percentage of earned premium, excluding overhead expenses.
- IBNR
- Incurred But Not Reported: reserves for claims costs yet to emerge in full.
- Attritional claims
- More frequent, lower-value claims, distinct from separately classified large and weather losses.
Choose the time structure
Build triangles on an accident or underwriting-period basis. Select monthly, quarterly or yearly origin and development periods to reflect the volume and maturity of the experience.
Group the claims that belong together
Separate or combine attritional, large and weather losses. Use portfolio fields such as product, peril, coverage or region to create development groups appropriate to the business.
Connect development with performance
Review development profiles against relevant benchmarks and select assumptions for ultimate claims, ultimate loss ratios and IBNR. Feed the selected ultimates and benchmarks back into portfolio analysis to inform underwriting decisions.
Flexible reserving views that stay connected to the portfolio
Let’s put it into practice
See how this could work for your portfolio
A portfolio challenge, an upcoming review or a different way of working. Let’s explore it together.
Book a demo